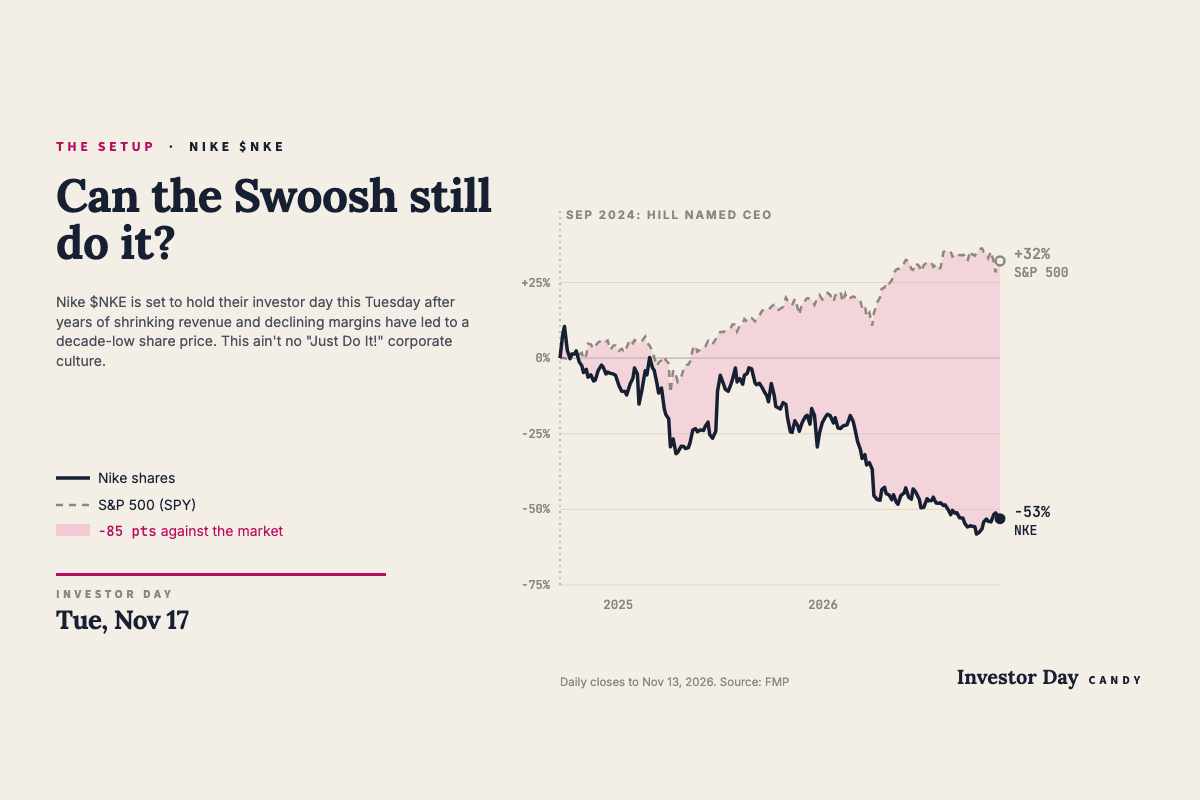
Nike $NKE is set to hold their investor day this Tuesday after years of shrinking revenue and declining margins have led to a decade-low share price. This ain't no "Just Do It!" corporate culture.
The Setup: FY27 revenue is guided down high single digits to about $43 billion, below FY21's level, and the EBIT margin will be near 5.5%, against 14.7% in FY22. The stock is 79% below its 2021 peak and has roughly halved under Elliott Hill, while adidas grows at double Nike's margin. Investors now accept the diagnosis. What they doubt is the calendar, because every timeline has slipped. Will they finally deliver a margin target with a year attached that holds up to analyst scrutiny?
Halved Twice. Revenue peaked at $51.4 billion in FY24. Profit fell further than sales. EBIT margin went from 12.7% in FY24 to 8.3% last year, and even that needed a $986 million tariff refund; without it the margin was about 6%. Gross margin was 40.8% before the refund, against 46% in FY22. Free cash flow fell from $6.6 billion to $2.2 billion, less than the $2.4 billion dividend. Meanwhile adidas is growing 11% currency-neutral this year at an 11.1% operating margin, and On grew 18% last quarter at a 22% EBITDA margin. This isn't just the cycle.
Some of it is working. Performance is a $16 billion business growing high single digits, Running added about $1 billion in five quarters, and North America is growing again. The trouble is everything else. Sportswear and Jordan, about half of revenue, are falling double digits. Greater China fell 26% last quarter. Converse sales dropped 31% last year to $1.2 billion, on $18 million of EBIT.
Goalposts on Wheels. The earnings calls read like a project plan that keeps slipping:
- December: "middle innings," guidance 90 days at a time, double-digit margins with no date.
- March: Hill said everyone expected "two years" and that's "where we're tracking." Guidance ran through December 2026: revenue down low single digits, earnings flattish.
- June: the revenue guide was cut to down low-to-mid single digits.
- October, under a new CFO: a high-single-digit decline for FY27, China getting worse, and pain that will "bleed a little bit into fiscal '28."
At $38 the stock trades at about 30x the midpoint of FY27 guidance. It's only about 16x what Nike would earn at a 10% EBIT margin on this year's lower sales. (The trailing P/E of 18 is flattered by the refund.)
Enter the Cost Guy. Hill spent 32 years in Nike sales and marketplace roles, and he pulled the levers you'd expect: wholesale, marketing, sport-led product. Dave Denton became CFO in August. He was Pfizer's CFO before that, and earlier at Lowe's and CVS, so his strengths are cost programs and capital allocation. Within six weeks he reset FY27 guidance and launched Pace: $2.5 billion of savings for about $1 billion of cost, mostly landing in FY29-30. He also promised a five-year financial framework. The Knight-controlled Class A shares elect three-quarters of the board, so no activist will force anything. A conservative reset is the best outcome on offer.
Get Some Heat? Nike lacks the resources to acquire some leading private brands like Vuori. Their last funding round valued it at $5.5 billion; with a premium, a deal is $7-10 billion. Already has $2B of debt coming due and not enough cash flow to cover the dividend so they can't get it done.
NikeSKIMS shows a partnership can bring heat without the price tag. And the heat Nike lacks is in Sportswear and Jordan, which no acquisition fixes. If they can find more of these it can help growth.